

Blogs
An ERP system should make business operations easier to manage. It should connect departments, provide reliable information, reduce manual work, and help management make better decisions.
But as a business grows, its ERP requirements also change. A system that worked well when the company was smaller may become difficult to manage when operations expand across products, warehouses, suppliers, locations, and sales channels.
Here are five signs that your business may have outgrown its current ERP system.
1. Your Teams Still Depend on Spreadsheets
Spreadsheets can be useful for small tasks, but they become a problem when they are being used to manage important business processes outside the ERP.
Too Much Manual Data Entry
If employees regularly export ERP data, update spreadsheets, and then share files between departments, there is a greater chance of errors and outdated information.
Finance, procurement, inventory, sales, and operations should be able to work with the same business data without maintaining separate versions of it.
2. You Cannot Get a Clear View of Operations
Management needs accurate information to understand what is happening across the business.
If it takes hours or days to prepare reports on inventory, sales, procurement, production, or financial performance, the ERP may no longer be meeting your reporting requirements.
Information Is Scattered Across Systems
Businesses often add separate tools as they grow. CRM, accounting software, warehouse systems, spreadsheets, and other applications may operate independently.
When these systems do not communicate properly, getting a complete picture of business performance becomes difficult.
3. Your Business Processes Require Too Many Workarounds
An ERP should support your business processes rather than forcing employees to constantly find ways around the system.
If teams are using manual approvals, duplicate entries, external spreadsheets, or unofficial processes to complete routine work, it may indicate that the ERP is not aligned with current operations.
Processes Have Changed Since Implementation
Your business may have added new products, warehouses, locations, suppliers, or sales channels since the ERP was implemented.
The system should evolve with those changes. If it cannot support new requirements without extensive workarounds, it may be time to review your ERP strategy.
4. Your ERP Cannot Scale With Business Growth
Growth often brings more transactions, users, locations, products, and operational complexity.
An ERP that worked for one location may struggle to support multiple warehouses or business units. Similarly, a system designed around a limited product range may become difficult to manage as product and inventory requirements increase.
Scalability Matters
Before replacing an ERP, businesses should evaluate whether the existing system can be upgraded, integrated, or reconfigured to support future requirements.
In some cases, optimization is enough. In others, a new ERP platform may be more practical.
5. Your ERP Does Not Support Better Decision-Making
An ERP should provide more than transaction processing. It should help management understand business performance.
If decision-makers cannot easily access accurate information about inventory levels, purchasing, production, sales, cash flow, or operational costs, the ERP may be limiting the business.
Better Data Leads to Better Control
Connected data allows businesses to identify problems earlier, monitor performance, and respond to operational changes faster.
The goal is not simply to have a newer ERP. The goal is to have a system that supports how the business operates today and where it plans to go next.
What Should You Do Next?
Outgrowing an ERP does not automatically mean that you need to replace it.
Start by reviewing your current processes, reporting requirements, integrations, user needs, and future growth plans. Identify where the existing system is creating delays, duplicate work, limited visibility, or unnecessary complexity.
For some businesses, ERP optimization or customization may solve the problem. Others may benefit from migration to a platform such as ERPNext .
The right decision depends on your processes, business size, industry, and long-term requirements. A proper ERP assessment can help you understand what needs to change before making a major technology investment.
Need Help With Your ERPNext Transformation?
If your current ERP is creating operational challenges, Indictrans Technologies can help you evaluate your requirements and identify the right path forward. As an experienced ERPNext service provider, Indictrans supports businesses with ERPNext implementation, customization, migration, integration, version upgrades, and ongoing support.
With experience across manufacturing, distribution, and retail, the team works around your existing processes and business requirements to build an ERP environment that is practical, scalable, and easier to manage.
Talk to Indictrans Technologies about your ERP requirements and explore the right approach for your business.
PW Consulting: Hand Trucks Market Hits USD 1,091M in 2025, Projected 3.85% CAGR Through 2032
By PW Consulting, 2026-09-16
Strategic Intelligence Report: The Hand Trucks Market 2026-2032 Outlook
Executive Overview: Navigating a Maturing Sector
The material handling sector stands at a critical juncture as we move through 2026. While often perceived as a commodity category, the hand trucks market represents a complex interplay of material costs, regulatory shifts, and evolving labor dynamics. For enterprise leaders, supply chain managers, and strategic planners, understanding the trajectory of this market is not merely about procurement—it is about securing operational resilience.
This analysis serves as an introduction to the PW Consulting latest comprehensive study on the Hand Trucks Market. The research is designed to equip decision-makers with the granular intelligence required to navigate the forecast period from 2026 to 2032. By examining historical performance trends and projecting future growth vectors, we provide a roadmap for capitalizing on market opportunities while mitigating exposure to volatile input costs and trade policy changes.
Our methodology combines rigorous primary research with advanced modeling techniques to ensure that the insights provided are actionable. In an environment where margin pressure is high and supply chain disruptions remain a constant threat, access to precise market intelligence is a competitive differentiator.
Market Trajectory and Economic Indicators
The historical data reveals a sector that has demonstrated resilience despite macroeconomic headwinds. Between 2020 and 2025, the global market for hand trucks navigated significant fluctuations in demand and supply chain stability. Starting from a base of approximately 935.5 million USD in 2020, the market exhibited a clear upward trajectory, reaching a valuation of 1091.0 million USD by 2025. This growth underscores the essential nature of manual material handling equipment across various industries.
Looking toward the forecast horizon, the momentum is projected to continue, albeit at a measured pace reflective of a mature industry. The market is anticipated to grow from 1167.27 million USD in 2026 to 1390.0 million USD by 2032. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 3.85 percent over the forecast period. While this growth rate may appear moderate compared to high-tech sectors, it represents substantial volume in absolute terms for manufacturers and investors focused on steady returns and market share consolidation.
It is important for stakeholders to interpret these figures within the context of broader economic conditions. The growth is not uniform across all timelines; there are expected variances as the market adjusts to new manufacturing capacities and shifting demand patterns. Understanding the timing of these peaks and troughs is crucial for capacity planning and inventory management.
Structural Segmentation and Value Chains
A deep dive into the structural composition of the market reveals distinct dynamics across material types, applications, and geographic regions. These segments do not perform in isolation; they are interconnected through supply chains and end-user requirements.
Hand Tools Market
Material Composition and Cost Drivers
The market is primarily divided by the construction material of the equipment. Steel remains a dominant force, reflecting its durability and cost-effectiveness for heavy-duty applications. Aluminum holds a significant position, valued for its lighter weight and corrosion resistance, particularly in scenarios where worker ergonomics and portability are priorities. Additionally, plastic and other composite materials constitute a portion of the market, often utilized for specific lightweight or specialized tasks. The choice of material is increasingly becoming a strategic decision influenced by raw material availability and tariff structures.
Application Verticals
Demand is driven by several key application verticals. Logistics and warehousing continues to be a primary consumer, driven by the need for efficient movement of goods within distribution centers. The retail sector represents another substantial chunk of demand, essential for stocking shelves and managing backroom operations. Furthermore, the industrial and construction sectors maintain consistent requirements for moving heavy equipment and materials on-site. Each vertical has unique specifications regarding load capacity, maneuverability, and durability, influencing the product mix required by manufacturers.
Regional Dynamics
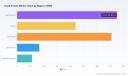
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America and Asia Pacific represent significant portions of the global volume, reflecting strong industrial bases and logistics networks in these regions. Europe maintains a steady demand profile supported by established manufacturing and retail infrastructures. Emerging markets in Latin America and the Middle East and Africa offer growth potential, though often at different scales of maturity. Understanding the regional weighting is essential for companies looking to expand their footprint or optimize their supply chain logistics.
Competitive Landscape and Strategic Moves
The competitive environment is characterized by a mix of established manufacturers and specialized providers. Market concentration indicates a moderately fragmented landscape, with the top three players holding a combined share of 25.5 percent and the top five holding 38.2 percent. This structure suggests that while there are dominant players, there is still room for niche providers and regional specialists to thrive.
Key Industry Players
Several companies define the current competitive arena, each bringing distinct strengths to the table.
Hand Trucks Market
- Harper Trucks: Based in Wichita, Kansas, this manufacturer is a pivotal figure in the industry, producing a significant portion of hand trucks sold in the United States. Their focus on heavy-duty hand trucks and appliance dollies positions them as a leader in high-volume utility solutions.
- Magliner: Located in Standish, Michigan, Magliner distinguishes itself through innovation. With over 4,000,000 possible custom builds, they offer convertible designs and innovative configurations that cater to specific user needs, emphasizing flexibility and customization.
- Vestil Manufacturing: Operating out of Angola, Indiana, Vestil boasts a massive manufacturing footprint with over 1,000 product lines and extensive square footage. They are a key supplier of industrial material handling equipment, including hand trucks and carts.
- American Cart and Equipment: Since 1997, this Archbold, Ohio-based producer has focused on heavy-duty hand trucks and multi-mover carts, with a strong emphasis on appliance and specialty carts manufactured in the United States.
- B&P Manufacturing: With facilities in the United States, B&P has been manufacturing hand trucks and material handling equipment since 1943. Their ISO 9001:2015 certification underscores a commitment to quality management and consistent production standards.
- Wesco Industrial Products: Based in North Wales, Pennsylvania, Wesco produces American-made hand trucks, including industrial duty, convertible, aluminum, and stair-climbing models, integrating hand trucks into a broader material handling portfolio.
Recent Strategic Developments
The competitive landscape is dynamic, with recent activity signaling shifts in strategy and capacity. In early 2025, Magliner introduced next-generation convertible hand truck models and new powered stair-climbing units, signaling a move toward enhanced functionality and powered solutions. Later in the year, Harper Trucks expanded its presence with advanced manufacturing technology and new product innovations, reinforcing its commitment to production efficiency.
Moving into 2026, strategic partnerships and capacity expansions have come to the forefront. B&P Manufacturing entered into a partnership to expand distribution and market position, aiming to broaden its reach. Simultaneously, Wesco Industrial Products implemented capacity expansion to increase production of hand trucks and related equipment. Vestil Manufacturing also released new innovative products, including hydraulic skid steer booms and electric tuggers, which complement hand truck-compatible material handling solutions. These moves indicate a sector preparing for increased demand and looking to diversify product offerings.
Regulatory and Macroeconomic Pressures
No strategic analysis is complete without addressing the external forces shaping the market. Regulatory changes and raw material costs are currently significant variables that influence pricing, sourcing, and ultimately, profitability.
Tariffs and Input Costs
A critical factor for manufacturers and buyers alike is the status of raw material tariffs. Effective March 2025, US Section 232 tariffs on aluminum and steel imports increased to 25 percent. This adjustment has direct implications for input costs for hand trucks and material handling equipment. For companies reliant on imported metals, this creates pressure on margins unless mitigated through supply chain adjustments or pricing strategies. Conversely, it may provide a protective advantage for domestic manufacturers who source materials locally, potentially altering the competitive balance between domestic and imported goods.
Trade Policy and Antidumping Duties
Trade policy remains in flux. The International Trade Commission initiated a five-year review on February 2, 2026, to determine the revocation of the antidumping duty order on hand trucks and parts from China. The outcome of this review could significantly impact the flow of imports and the pricing dynamics within the US market. Stakeholders must monitor this development closely, as a revocation could lower costs for imported units, while a continuation would maintain the current protective barrier for domestic producers.
Safety Standards and Compliance
Compliance with safety standards is non-negotiable in industrial environments. ISO 3691-5:2014 provides safety requirements for pedestrian-propelled trucks, including hand trucks. With verification standards updated for industrial use, manufacturers and users must ensure that equipment meets these criteria to avoid liability and ensure worker safety. Adherence to these standards is not just a regulatory requirement but also a market expectation, particularly in large logistics and industrial contracts.
Strategic Implications for 2026 Decision Makers
Synthesizing the market size, competitive actions, and regulatory environment, several strategic imperatives emerge for organizations operating in or utilizing the hand trucks market in 2026.
- Supply Chain Diversification: Given the tariff environment and potential trade policy shifts, relying on a single source for materials or finished goods introduces risk. Diversifying suppliers across regions or investing in domestic manufacturing partnerships can buffer against tariff shocks and supply disruptions.
- Product Mix Optimization: The demand for customization and specialized applications is evident from competitor moves. Companies should evaluate whether their current product portfolios align with the needs of high-growth verticals like logistics and warehousing. Investing in convertible designs or powered accessories could open new revenue streams.
- Cost Management and Pricing Strategy: With input costs fluctuating due to metal tariffs, precise cost modeling is essential. Pricing strategies must account for potential volatility in steel and aluminum markets while remaining competitive. Understanding the regional cost structures can help in negotiating better terms with suppliers.
- Monitoring Regulatory Developments: The ongoing antidumping duty review and safety standard updates require active monitoring. Changes in these areas can alter the competitive landscape overnight. Proactive engagement with regulatory updates allows companies to adjust their sourcing and compliance strategies ahead of competitors.
- Capacity Planning: As competitors like Wesco and Harper Trucks expand capacity, market supply may increase. Understanding the timing of these expansions relative to demand growth helps in planning inventory levels and avoiding oversupply or stockouts.
Conclusion: The Value of Deep Intelligence
The hand trucks market is more than a simple transaction of goods; it is a sector influenced by global trade policies, material science, and industrial demand shifts. The data points from 2020 through the 2032 forecast provide a skeleton of growth, but the flesh and blood of strategy lie in the details. Knowing the aggregate market size is useful, but understanding the specific dynamics of steel versus aluminum demand, the nuances of regional regulatory impacts, and the strategic intent of key competitors is where real value is created.
PW Consulting latest report on the Hand Trucks Market delves into these specifics, offering a level of detail that general market summaries cannot provide. From granular segmentation analysis that respects the confidentiality of specific regional percentages to deep dives into the operational strategies of key players, this research is built for action.
For enterprises aiming to secure their supply chains, optimize procurement costs, or identify new market entries, the margin for error is small. The insights contained within this study are designed to reduce that margin. We invite you to access the full research document to unlock the complete suite of data, forecasts, and strategic recommendations tailored to your specific operational context.
For detailed analysis of this topic, please visit the official page: Hand Trucks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The global pumps market is poised for consistent revenue growth from 2020 to 2035. Starting at approximately USD 62,500 Million in 2025, the market is forecast to reach USD 95,600 Million by 2035, reflecting a CAGR of about 4.3%. Incremental gains are propelled by infrastructure investments, rising industrialization, and technological innovation. Leading vendors prioritize sustainability, digitalization, and regional market expansion to capture new revenue streams and reinforce their competitive positioning over the forecast period.
Read More - https://bussinessinsights.com/research-report/global-pumps
Water & wastewater management dominates pump applications in 2025, propelled by urbanization, infrastructure investments, and smart city initiatives. Oil & gas accounts for a substantial share due to ongoing exploration, refining, and downstream processing. Chemical, power generation, food & beverage, and other industries also drive growth, amplifying the need for diversified and robust pump solutions. Market leaders are customizing products for critical sectors, with particular focus on digital integration, safety, and reliability improvements, ensuring industry compliance and operational efficiency.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-pumps
Frequently Asked Questions
Who are the key players in Global Pumps industry?
The top five players in the Global Pumps industry are Grundfos, Xylem Inc., Flowserve Corporation, Sulzer Ltd., and KSB SE & Co. KGaA. These companies have significant global presence, strong R&D, and robust distribution networks, allowing them to lead in the technological advancement and deployment of pump solutions worldwide.
What is the Global Pumps growth?
The Global Pumps market has shown steady growth, with a CAGR of around 5% in recent years. In 2023, Xylem Inc. reported a revenue increase driven by demand in water and wastewater management, indicating strong expansion due to rising urbanization and industrialization worldwide.
Which segment accounted for the largest Global Pumps share?
Water and wastewater treatment applications accounted for the largest share in the Global Pumps market. This segment is rapidly expanding due to global concerns over water scarcity, stricter environmental standards, and government investments in water infrastructure, making it the dominant application for pump technologies.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Biosurfactant Sales Hit $9.02B in 2025, Forecast to $16.93B by 2032 at 9.41% CAGR
By PW Consulting, 2026-09-16
Biosurfactants Market 2026: Strategic Intelligence for the Green Chemistry Transition
The global chemical landscape is undergoing a paradigm shift, driven by stringent environmental regulations, consumer demand for sustainable products, and the urgent need to reduce reliance on petrochemical derivatives. At the forefront of this transition lies the biosurfactant sector. For strategic decision-makers operating in 2026, understanding the trajectory of this market is not merely an academic exercise but a critical component of supply chain resilience and product portfolio optimization. PW Consulting's latest market research provides a comprehensive roadmap for navigating these complexities, offering data-driven insights that extend beyond surface-level trends to uncover underlying structural shifts.
This analysis serves as a strategic overview of the biosurfactant landscape, synthesizing historical performance, growth projections, and competitive dynamics. It is designed to equip industry leaders with the context necessary to make informed capital allocation and product development decisions in a rapidly evolving environment.
Market Trajectory and Growth Momentum
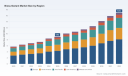
The biosurfactant market has demonstrated consistent resilience and expansion over the past half-decade. Historical data from 2020 through 2025 indicates a steady upward climb in revenue, reflecting the gradual but firm integration of bio-based solutions into mainstream industrial and consumer applications. The market valuation has grown from approximately $5.75 billion in 2020 to an estimated $9.02 billion by 2025. This historical performance lays the groundwork for an aggressive forecast period extending through 2032.
Looking ahead to the 2026-2032 forecast period, the trajectory suggests an acceleration in adoption rates. The market is projected to reach $10.1 billion in 2026, growing to nearly $16.93 billion by 2032. This expansion is underpinned by a compound annual growth rate (CAGR) of 9.41 percent. Such growth rates indicate that biosurfactants are moving from niche applications to mainstream commoditization in specific high-value segments. For stakeholders, this implies that the window for establishing early-mover advantages in supply chain partnerships and proprietary formulation technologies is narrowing.
It is crucial to note that this growth is not uniform across all vectors. While the aggregate numbers paint a picture of robust health, the underlying distribution of revenue across regions and applications reveals strategic opportunities that remain partially obscured without granular analysis. The overall market size figures provide a macro foundation, but the real strategic value lies in understanding where the marginal growth dollars are originating and which segments are driving the CAGR.
Industry Dynamics and Regulatory Tailwinds
The acceleration of the biosurfactant market is inextricably linked to a confluence of regulatory pressures and raw material innovations. Several key dynamics are reshaping the cost structures and compliancerequirements for manufacturers, creating both headwinds for traditional petrochemical surfactants and tailwinds for bio-based alternatives.
Regulatory frameworks in major markets have tightened significantly. In Europe, the EU REACH regulations have imposed stricter rules on poorly biodegradable surfactants, prompting a rapid substitution effect. Companies utilizing traditional surfactants face increasing compliance costs and reputational risks, driving them to seek biodegradable alternatives. Furthermore, the EU Industrial Emissions Directive and REACH Annex XVII have introduced new benchmarks requiring biodegradable surfactant alternatives in various industrial processes. These regulatory shifts are not merely compliance checkboxes but are fundamentally altering the addressable market for biosurfactants.
On the policy front, the EU Renewable Energy Directive III has designated glycerol-based biosurfactant products as advanced bio-based chemicals. This designation unlocks carbon credits, improving the economic viability of production and incentivizing investment in glycerol-based pathways. Similarly, in the United States, the EPA Safer Choice program has expanded its listings of green surfactants, enabling biosurfactants like rhamnolipids to serve as compliant alternatives for manufacturers seeking eco-labels.
Raw material dynamics are also playing a pivotal role. A significant development in fermentation economics involves the substitution of crude glycerol from biodiesel production for refined vegetable oils in rhamnolipid fermentation. This shift cuts feed costs substantially, resulting in lower biosurfactant ex-factory prices. This cost optimization enhances the competitiveness of biosurfactants against their synthetic counterparts, removing one of the primary barriers to adoption in price-sensitive applications.
Competitive Landscape and Strategic Positioning
The competitive environment in the biosurfactant market is characterized by a mix of established chemical giants and specialized biotechnology firms. Concentration metrics indicate a consolidated landscape where a small number of players hold significant sway. The CR3 and CR5 concentration ratios both stand at 40.7 percent, suggesting that while the top tier is influential, there is substantial room for mid-tier and niche players to capture value through specialization and regional focus.
Leading incumbents are leveraging their scale and technical expertise to secure market share. Evonik Industries AG, headquartered in Essen, Germany, focuses on producing high-purity rhamnolipids and sophorolipids from renewable corn feedstocks via industrial-scale fermentation at its Slovak plant. This capability allows them to supply consistent, high-quality volumes to demanding sectors. Similarly, Solvay S.A. in Brussels provides biosurfactants and bio-based chemical solutions for both industrial and consumer markets, integrating these products into broader sustainable portfolios. Croda International Plc, based in the UK, produces glycolipid biosurfactants and offers technical support specifically for detergent and personal care uses, highlighting the importance of application-specific know-how.
In personal care and premium applications, Kaneka Corporation and Givaudan SA are prominent. Kaneka manufactures high-purity biosurfactants for premium cosmetic applications, while Givaudan provides biosurfactants for premium personal care and clean-label products, leveraging their fragrance and flavor dominance to cross-sell sustainable ingredients. Stepan Company, operating out of Northfield, Illinois, offers rhamnolipid biosurfactants derived from renewable feedstocks targeted at detergents and personal care, aligning their portfolio with high-volume consumer goods.
Specialized producers are also making significant moves. Jeneil Biotech Inc. and Biotensidon GmbH focus on rhamnolipid and microbial biosurfactants respectively, catering to eco-friendly formulations and eco-labeled detergents. AGAE Technologies, LLC has been particularly active in capacity expansion. In early 2025, they inaugurated the largest retrofitted manufacturing plant in Asia with annual capacity exceeding 1,000 metric tons of rhamnolipid biosurfactants. They subsequently opened a new 3,800 m² plant in Asia with similar capacity and announced US facility plans. Dispersa Inc. in Canada transitioned from pilot reactors to a 50,000 L commercial-scale system targeting 100 metric tons per year of sophorolipids. These capacity expansions signal a shift from R&D curiosity to commercial readiness.
Regional players are also strengthening their positions. Saraya Co., Ltd. and Allied Carbon Solutions Co., Ltd. in Japan specialize in MES and other biosurfactants for industrial cleaning and detergent formulations. Shaanxi Deguan Biotechnology Co., Ltd. in China produces sophorolipid biosurfactants for industrial and personal care markets. Holiferm Ltd. in the UK specializes in sophorolipid production for mass-market eco-friendly surfactants. Locus Fermentation Solutions in the USA develops EPA-approved biosurfactants for personal care and industrial applications. These diverse geographic footprints suggest that supply chain localization is becoming a strategic priority for end-users seeking to mitigate logistics risks.
Report Scope and Methodology
To navigate this complex ecosystem, comprehensive intelligence is required. The PW Consulting Biosurfactant Market research report is structured to provide actionable intelligence across multiple dimensions. The analysis covers a detailed historical review from 2020 to 2025, establishing a baseline for performance evaluation. This historical context is critical for validating growth models and understanding the impact of recent regulatory changes on market uptake.
The forecast period extends from 2026 through 2032, allowing stakeholders to model long-term investment returns and capacity planning. The report dissects the market across key segmentation vectors including region, type, and application. While aggregate growth is positive, understanding the split between Glycolipids, Lipopeptides, and Phospholipids is essential for R&D focus. Similarly, analyzing demand drivers across Detergents, Personal Care, Food Processing, and Oil & Petroleum sectors reveals where margin opportunities are most pronounced. Geographic analysis covers Europe, North America, Asia Pacific, Latin America, and the Mideast and Africa, highlighting regional regulatory nuances and supply chain dynamics.
Microbial Biosurfactants Market
Beyond market sizing, the report includes detailed profiles of key companies, assessing their strategic moves, capacity expansions, and product offerings. Recent developments such as joint ventures, new plant inaugurations, and technology transitions are tracked to provide real-time intelligence on competitive momentum. The analysis also incorporates qualitative dynamics regarding raw material sourcing, regulatory impacts, and technological shifts that quantitative data alone cannot capture.
Biosurfactant Market
Strategic Implications for 2026 Decision Makers
For executives and strategists operating in 2026, the biosurfactant market presents a clear imperative: sustainability is no longer optional, and bio-based chemistry is becoming economically viable. The convergence of regulatory pressure, cost optimization through raw material substitution, and capacity expansion by key players creates a inflection point. Companies that hesitate to integrate biosurfactants risk facing higher compliance costs and supply chain vulnerabilities as petrochemical alternatives face stricter scrutiny.
However, the market is not monolithic. The presence of specialized players alongside giants suggests that partnership strategies will be crucial. A detergent manufacturer may not need to become a fermentation expert but can leverage partnerships with firms like Jeneil Biotech or AGAE Technologies to secure supply. Conversely, ingredient suppliers must navigate the varying requirements of personal care versus industrial cleaning applications, as purity and performance specifications differ significantly.
The data suggests that Asia Pacific and Europe remain critical theaters for growth, driven by both consumption patterns and regulatory leadership. Yet, detailed regional splits and application-specific penetration rates contain the nuanced intelligence required to prioritize specific markets. Access to the full dataset is necessary to identify the specific high-growth pockets within the broader $16.93 billion endpoint.
Investment in capacity, whether through CAPEX or joint ventures, must be timed against the demand curve. The recent capacity expansions by AGAE, Dispersa, and Croda indicate that the supply side is preparing for the forecasted demand. Decision-makers must assess whether their own demand projections align with this incoming supply to avoid market saturation in specific niches or, conversely, to secure offtake agreements before capacity tightens.
Accessing Complete Intelligence
While this overview highlights the macroeconomic trends and competitive dynamics, the full strategic value of the market research lies in the granular data. Detailed segmentation splits, specific regional revenue contributions, and application-level growth rates are essential for building precise financial models and go-to-market strategies. The top-line figures provide confidence in the sector's direction, but the bottom-line details drive allocation decisions.
PW Consulting's comprehensive Biosurfactant Market report offers the depth required to move from general awareness to specific action. It provides the segmentation data, company profiles, and dynamic analysis needed to outperform competitors who rely on aggregate industry knowledge. For organizations seeking to capitalize on the 9.41 percent growth trajectory and navigate the regulatory landscape effectively, acquiring the full intelligence suite is the logical next step. The window to secure strategic positioning in this green chemistry transition is open, but it requires data-backed conviction to act decisively.
For detailed analysis of this topic, please visit the official page: Biosurfactant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
From 2020 to 2035, the global LNG bunkering equipment market is projected to expand substantially, with revenue rising from USD 1,320 Million in 2020 to nearly USD 5,880 Million by 2035. This surge is underpinned by rapid LNG infrastructure expansion, ship retrofitting programs, and increasingly supportive regulatory frameworks globally. The consistent double-digit CAGR reflects ongoing investments, port upgrades, and the accelerating replacement of high-emission fuels in maritime shipping worldwide.
Read More - https://bussinessinsights.com/research-report/global-lng-bunkering-equipment-
Ports remain the dominant application for LNG bunkering equipment, reflecting their pivotal role in global trade and marine fuel transition initiatives. Terminals and ships are also notable, as expanding global fleets and regulatory compliance foster infrastructure upgrades. Ferries and offshore platforms are generating additional equipment demand as LNG adoption spreads to varied vessel types. The continued expansion of storage facilities supports supply chain resilience, further anchoring market expansion across applications.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-lng-bunkering-equipment-
Frequently Asked Questions
Who are the key players in Global LNG Bunkering Equipment industry?
The top five players in the global LNG bunkering equipment industry are Wärtsilä, Shell, TotalEnergies, Chart Industries, and Kawasaki Heavy Industries. These companies dominate the market through advanced LNG solutions, extensive global networks, continual product innovation, and strong investments in environmentally sustainable marine fuel technology.
What is the Global LNG Bunkering Equipment growth?
The Global LNG bunkering equipment market has shown significant growth, especially due to Shell's expansion projects in Europe and Asia during 2023. Rising regulatory pressure for cleaner marine fuels and accelerated fleet conversions have pushed the market toward a robust double-digit annual growth rate.
Which segment accounted for the largest Global LNG Bunkering Equipment share?
The ship-to-ship (STS) bunkering segment holds the largest market share in the global LNG bunkering equipment space. Its dominance is due to high flexibility, growing adoption by major ports, and efficiency in refueling large vessels, making it the preferred application for international shipping routes globally.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: FeSi Powder Market Hits $1,554.12M in 2025, Projects 5.2% CAGR to $2,193.59M
By PW Consulting, 2026-09-16
Strategic Horizons: Navigating the Ferrosilicon Powder Market in 2026 and Beyond
The global ferrosilicon powder market stands at a critical inflection point. As industries ranging from steelmaking to mineral processing demand higher precision and regulatory compliance, understanding the trajectory of this specialized materials sector is no longer optional—it is a strategic imperative. PW Consulting's latest comprehensive market research offers a definitive guide for stakeholders preparing to navigate the complexities of the 2026-2032 forecast period.
Iron Powder Market
This analysis serves as a strategic primer, outlining the macroeconomic currents, competitive tensions, and regulatory shifts that will define the landscape. For decision-makers seeking granular data to inform capacity planning, supply chain optimization, or market entry strategies, this research provides the foundational intelligence required to act with confidence.
Market Trajectory and Growth Dynamics
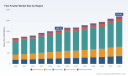
The historical performance of the ferrosilicon powder market demonstrates a consistent upward trajectory, reflecting the material's entrenched role in modern industrial applications. Between 2020 and 2025, the market expanded from approximately 1,190.55 million USD to 1,554.12 million USD, showcasing resilience even during periods of global economic volatility. This growth stabilization sets a robust baseline for the forecast period.
Looking ahead to 2032, the market is projected to reach a valuation of 2,193.59 million USD. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 5.2% over the forecast period. Such growth indicates a healthy demand environment, though it also suggests that early movers who secure supply chain advantages will capture disproportionate value. The acceleration is not uniform; it is being reshaped by geographical production shifts and evolving technical requirements in downstream sectors.
For corporate strategists, the key takeaway lies beyond the headline numbers. The growth trajectory signals sustained demand but also highlights the necessity of efficiency. As volumes increase, margins depend heavily on navigating input cost fluctuations and regulatory hurdles, which were notably intense in late 2025.
Segmentation and Application Nuances
While the aggregate market size provides a macro view, the real strategic opportunities lie in understanding the differential growth rates across product types and application verticals. The market is broadly categorized by production technology and end-use industry, each facing distinct demand drivers and technical barriers.
In terms of product type, the market is dominated by atomized ferrosilicon powder, which continues to hold the largest revenue share due to its widespread application in dense media separation and high-precision metallurgical processes. Milled ferrosilicon powder and other specialized types constitute significant but smaller segments, often catering to niche requirements where particle size distribution and purity are critical differentiators. The choice between atomized and milled forms often depends on the specific density and flow characteristics required by the downstream application, making technical specification intelligence vital for procurement teams.
Application-wise, the metallurgy sector remains the primary consumption engine. This includes deoxidation and inoculation processes in steelmaking, where consistent powder quality directly impacts final product integrity. The machinery industry and other specialized sectors follow, utilizing ferrosilicon powder for alloy production and specific industrial manufacturing processes. The interdependence between steel production cycles and ferrosilicon powder demand means that stakeholders must monitor broader industrial metal cycles closely.
PW Consulting's report delves deep into these segmentation splits, offering detailed revenue analysis and volume estimates that are essential for identifying high-growth niches. However, understanding the specific value contributions of each region or application segment requires access to the full dataset, as these figures fluctuate based on real-time supply chain adjustments and regional policy interventions.
Competitive Landscape and Strategic Positioning
The ferrosilicon powder market is characterized by a moderately concentrated competitive structure. With the top three players holding approximately 32.5% of the market share and the top five controlling around 38.7%, the landscape offers room for both established giants and agile regional specialists to compete. This concentration level suggests that while scale provides advantages in distribution and cost management, specialized technical capability and regional proximity remain significant differentiators.
Several key companies define the current competitive boundaries. DMS Powders, based in South Africa, stands out as a leading producer specifically focused on milled and atomized ferrosilicon powders for dense media separation applications in mining. Their product grades, ranging from coarse to fine cyclone specifications, highlight the technical granularity required in the mining sector. Meanwhile, European industrial giants like Elkem ASA and Finnfjord AS maintain strong footholds in metallurgical applications, producing ferrosilicon powders for deoxidation and inoculants. Elkem's recent operational decisions reflect the broader industry caution; in October 2025, the company partially curtailed production at its Rana plant in Norway and its Iceland facility, citing market conditions and the impact of EU safeguard measures.
Ferroglobe PLC and OM Holdings Ltd represent significant cross-regional capabilities. Ferroglobe, headquartered in the United Kingdom, supplies powders for steelmaking deoxidation and foundry uses, leveraging integrated production networks. OM Holdings, based in Singapore, serves as a key supplier for steel and alloy production, bridging Asian demand with global supply. On the high-purity flank, Stanford Advanced Materials in the United States supplies high-purity Ferro Silicon Powder with purity levels reaching 99% for specialized deoxidation needs, targeting segments where impurity control is paramount.
In Asia, particularly China, manufacturers like Anyang Lishi Industrial Co., Ltd. and Zhenan Metallurgy Co., Ltd. play crucial roles. Anyang Lishi is a notable manufacturer and exporter of both atomized and milled ferrosilicon powders for metallurgical and electrode applications. Zhenan Metallurgy focuses on low-aluminum ferrosilicon powder, catering to specific steelmaking requirements where aluminum content must be strictly controlled. The strategic positioning of these Asian players is critical, given the region's volume dominance in global supply.
Understanding the specific capacity, export capabilities, and proprietary grade portfolios of these competitors is essential for any market entry or expansion strategy. Our full report provides detailed competitor profiling, including SWOT analyses and strategic moves that are not publicly aggregated in general market summaries.
Regulatory Shifts and Industry Dynamics
The operating environment for ferrosilicon powder is undergoing significant transformation due to regulatory interventions and raw material dynamics. These factors introduce both risks and opportunities that must be modeled into any forward-looking strategy.
One of the most impactful recent developments occurred in November 2025, when the European Commission imposed safeguard measures on ferro-silicon imports, including powder forms. The EU established three-year tariff-rate quotas and implemented out-of-quota variable duties based on a price threshold of 2,408 USD per ton. This move is designed to protect local producers but introduces immediate complexity for importers and downstream users in Europe. The ramifications were felt quickly; Elkem ASA's production curtailment in late 2025 was partially attributed to the uncertainty generated by these safeguard measures.
Simultaneously, regulatory scrutiny is increasing in the supply source regions. Starting January 2026, China introduced new export license rules for ferrosilicon. These regulations require detailed specifications for exports, including particle size for FeSi products. Furthermore, batch-specific checks are now mandated for aluminum, calcium, phosphorus, and particle size for grades with 75% Si or higher. For global buyers, this means supply chain verification processes must be tightened, and lead times may be affected by administrative compliance. Anyang Lishi Industrial Co., Ltd. highlighted these changes in December 2025, signaling a shift toward stricter trade governance.
Infrastructure developments also signal shifting supply centers. In November 2025, Kazakhstan launched a new ferroalloys plant in Pavlodar. This facility, representing a 177 million USD investment, is designed to produce high-grade FeSi75 at an annual capacity of 240,000 tons for export. This expansion adds new volume to the global market and potentially alters trade flows, particularly for buyers seeking alternatives to traditional supply hubs.
On the technical application side, the fundamental utility of the material continues to drive demand stability. For instance, in dense media separation (DMS) applications within mining, powdered ferrosilicon is mixed with water to form a slurry used for density adjustment and mineral separation. This specific application requirement ensures that demand from the mining sector remains correlated with mineral processing activity, which varies by commodity cycles.
Strategic Implications for 2026 Decision Making
For corporate leaders, the convergence of these factors creates a complex operational environment. The 5.2% CAGR suggests that the market is growing faster than general industrial inflation, implying real demand expansion. However, the regulatory barriers in key markets like Europe and the stricter export controls from China mean that supply security is becoming as important as price competitiveness.
Companies must now evaluate their sourcing strategies with a multi-regional lens. Relying on a single supply corridor introduces vulnerability to tariff shocks and export licensing delays. The entry of new capacity in Central Asia offers diversification potential, but requires thorough due diligence on quality consistency and logistics reliability. Furthermore, the distinction between atomized and milled powders is not merely technical; it affects compatibility with existing processing equipment and compliance with specific metallurgical standards.
Procurement teams need to factor in the cost implications of the EU safeguard measures. For European manufacturers, the tariff structure may influence decisions on whether to source domestically or import from outside quota allocations. For exporters, understanding the price threshold mechanisms is critical to maintaining margin integrity. Meanwhile, the focus on purity and particle size specifications, driven by both regulatory checks and end-user performance requirements, elevates the importance of supplier technical audits.
PW Consulting's full market research report goes beyond these high-level dynamics to provide the specific quantitative forecasting and segmentation data necessary to model these scenarios. We analyze historical consumption patterns from 2020 to 2025, benchmark them against the forecast period through 2032, and isolate the growth contributions of each segment. This level of detail allows stakeholders to stress-test their strategies against various regulatory and demand outcomes.
Conclusion: The Value of Granular Intelligence
The ferrosilicon powder market offers compelling growth opportunities, but realizing them requires more than a top-line growth rate. It demands a nuanced understanding of who is producing what, where trade barriers are being erected, and how technical specifications are evolving to meet downstream needs. The competitive landscape is stable yet reactive, with major players adjusting production and trade strategies in response to the new regulatory normal.
Fesi Powder Market
As 2026 unfolds, the ability to access precise market intelligence will differentiate between organizations that merely react to market shifts and those that proactively shape their position within them. PW Consulting's in-depth analysis provides the roadmap for this navigation, offering the data density and strategic context required for high-stakes decision making.
To access the complete dataset, including detailed regional revenue breakdowns, specific application volume estimates, and comprehensive competitor strategic profiles, please refer to the full PW Consulting Fesi Powder Market Research Report. The insights contained within are designed to empower your next strategic move with precision and confidence.
For detailed analysis of this topic, please visit the official page: Fesi Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The global electric boom lifts market shows a strong upward trajectory through 2020-2035. Market revenue is estimated at $2,350 Million in 2025, up from $1,720 Million in 2020, and projected to reach $6,720 Million by 2035. This robust growth is fueled by rapid infrastructure development, urbanization in key markets, and stringent emission standards pushing the transition from diesel to electric models. Major market players are continually investing in R&D, product line expansions, and strategic partnerships to capture new opportunities and optimize revenue streams across regions.
Read More - https://bussinessinsights.com/research-report/global-electric-boom-lifts-market
Construction remains the dominant application for electric boom lifts, representing over one-third of market demand in 2025, due to increased infrastructure projects and urban redevelopment. Utilities and industrial applications are also substantial, as maintenance, energy, and logistics sectors emphasize safety, productivity, and sustainability. The ongoing shift towards automation and eco-compliance in logistics and warehousing is expected to further amplify market penetration for electric-powered lifts in these domains.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-electric-boom-lifts-market
Frequently Asked Questions
Who are the key players in Global Electric Boom Lifts Market industry?
The key players in the Global Electric Boom Lifts Market include JLG Industries, Genie (Terex Corporation), Haulotte Group, Dingli, and Sinoboom. These companies focus on innovation, safety features, and expanding their electric boom lift product portfolios to cater to the growing demand for environmentally friendly and efficient aerial work platforms worldwide.
What is the Global Electric Boom Lifts Market growth?
The Global Electric Boom Lifts Market has shown significant growth in recent years, driven by the increasing adoption of green construction equipment. In 2023, companies like Genie (Terex Corporation) reported higher sales due to growing infrastructure projects and rising preference for electric-powered machinery, projecting a healthy CAGR through 2030.
Which segment accounted for the largest Global Electric Boom Lifts Market share?
The construction segment accounted for the largest market share in the Global Electric Boom Lifts Market. Driven by rapid urbanization and increasing investments in commercial and residential infrastructure projects, electric boom lifts are widely used for tasks such as building maintenance, installation, and finishing work at heights.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global hydraulic cylinder market is projected to reach $22,130 Million by 2025, up from $16,300 Million in 2020. By 2035, revenues are anticipated to climb to $41,750 Million, driven by technological advances and broadening industrial applications. The revenue growth trajectory reflects ongoing modernization in construction, agriculture, and heavy machinery sectors worldwide, alongside widespread adoption of energy-efficient and smart hydraulic systems. Robust demand is expected to continue across both mature and emerging economies as the focus on automation, digitalization, and sustainability increases investment and replacement cycles for hydraulic equipment.
Read More - https://bussinessinsights.com/research-report/global-hydaulic-cylinder
In 2025, the construction sector dominates hydraulic cylinder application share due to substantial infrastructure development and heavy equipment upgrades globally. Agriculture and industrial automation collectively represent over a third of market utilization, fueled by farm mechanization and manufacturing digitalization. Mobile and mining equipment applications are also key, as innovative cylinder technologies support modernization and safer, more efficient work in demanding environments. Aerospace & defense hold a niche but technologically advanced segment, leveraging high-precision, lightweight cylinders. This distribution demonstrates substantial reliance on hydraulic cylinders for both traditional heavy industries and advanced automation processes.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-hydaulic-cylinder
Frequently Asked Questions
Who are the key players in Global Hydraulic Cylinder industry?
The top five players in the global hydraulic cylinder industry include Bosch Rexroth, Parker Hannifin, Eaton Corporation, Caterpillar Inc., and Enerpac. These companies are leading due to their extensive product portfolios, innovative technologies, strong distribution networks, and key strategic partnerships across various industrial sectors.
What is the Global Hydraulic Cylinder growth?
The global hydraulic cylinder market has been experiencing steady growth, with a notable surge driven by the rising demand in construction and mining. For example, Parker Hannifin reported increased orders in 2023, attributing growth to infrastructural projects and increased automation adoption in developing regions.
Which segment accounted for the largest Global Hydraulic Cylinder share?
Mobile applications, particularly in construction and agriculture machinery, accounted for the largest share of the global hydraulic cylinder market. The demand for powerful, reliable hydraulic systems in equipment like excavators, loaders, and tractors continues to fuel segment dominance due to ongoing development projects worldwide.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting Report: Manual Motor Starters Market Hits $630M in 2025, Projected 4.5% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Next Decade: Strategic Insights into the Global Manual Motor Starters Market (2026-2032)
The industrial landscape is undergoing a profound transformation, driven by the dual engines of automation and electrification. At the heart of this shift lies the fundamental infrastructure of motor control. For enterprise decision-makers, understanding the trajectory of the Manual Motor Starters Market is not merely an exercise in supply chain management; it is a strategic imperative that influences capital expenditure planning, safety compliance, and operational resilience. PW Consulting is proud to introduce our latest comprehensive market research study, designed to equip leadership teams with the actionable intelligence needed to thrive in the forecast period of 2026 through 2032.
This report serves as a critical navigational tool for stakeholders ranging from procurement directors to strategic planners. By analyzing historical performance from 2020 to 2025 and projecting forward, we uncover the underlying currents shaping the industry. The market, valued at approximately 630.0 Million USD in the base year of 2025, is poised for steady expansion. Our forecast models indicate a trajectory moving toward 857.0 Million USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 4.5 percent, signaling a mature yet consistently evolving sector where reliability and compliance drive demand rather than volatile speculation.
For organizations operating within or alongside the industrial manufacturing, oil and gas, water management, and mining sectors, these figures represent more than just top-line revenue. They reflect the ongoing replacement cycles of aging infrastructure, the integration of new safety standards, and the increasing complexity of motor protection requirements. This introduction provides a high-level overview of the strategic landscape, but the full depth of this intelligence is contained within the full report. The following analysis highlights the key themes our research unpacks in detail.
Macroeconomic Trajectory and Market Stability
The Manual Motor Starters Market has demonstrated remarkable resilience over the past five years. From 2020 to 2025, the market navigated global supply chain disruptions and economic fluctuations while maintaining a positive growth curve. The jump from 582.19 Million USD in 2024 to 630.0 Million USD in 2025 highlights a period of recovery and accelerated adoption. As we look toward 2026, the market is expected to reach 659.77 Million USD, setting the stage for a decade of incremental but significant growth.
This stability is crucial for long-term planning. Unlike high-volatility technology sectors, the demand for manual motor starters is tied to fundamental industrial output. The forecast period suggests that while the percentage growth may not be explosive, the absolute value addition is substantial. Companies that align their inventory and product development strategies with this steady 4.5 percent CAGR can optimize cash flow and reduce the risk of overstocking or undercapacity. However, realizing these benefits requires a nuanced understanding of where the growth is originating, which varies significantly by technology type and application vertical.
Manual Motor Starters Market
Segmentation Dynamics: Type and Application
A superficial view of the market hides the complex interplay between different product types and end-use applications. Our research dives deep into these segmentation splits to reveal where the highest value opportunities lie. The market is broadly categorized by technology, with AC Manual Motor Starters continuing to dominate the revenue share due to their widespread use in standard industrial power systems. However, the nuances within DC and other types offer specific niches for specialized engineering firms.
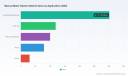
Similarly, the application landscape is diverse. Industrial manufacturing remains a primary driver, reflecting the need for cost-effective motor control in high-volume environments. Yet, sectors such as Oil and Gas and Water and Wastewater are critical growth engines due to stringent safety regulations and the harsh operating conditions that require robust starter solutions. Mining operations also contribute a significant portion of demand, particularly in regions undergoing infrastructure development.
Understanding the revenue contribution of each segment is vital for targeting. For instance, knowing which application vertical is expanding fastest can help manufacturers tailor their sales strategies and technical support teams. However, the specific percentage allocations and exact valuation figures for each region and application are proprietary data points that require the full report to access. This level of granularity allows competitors to benchmark their performance against the market average and identify untapped potential in specific verticals.
Regional Landscape and Distribution Channels
Geography plays a pivotal role in market dynamics. The global footprint of manual motor starters is uneven, reflecting the varying stages of industrialization and infrastructure investment across continents. Our analysis covers key regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a unique set of challenges and opportunities, from regulatory compliance in Europe to cost-sensitive competition in Asia Pacific.
Motor Control Centers Mcc Market
Europe, for example, often leads in terms of advanced safety standards and premium product adoption, while other regions may prioritize volume and affordability. The distribution of market revenue across these geographies influences where companies should focus their marketing spend and logistical hubs. Supply chain localization is becoming increasingly important as trade policies shift and customers demand faster delivery times.
Our report provides a detailed breakdown of regional market sizes and growth rates. This information is essential for multinational corporations deciding on regional expansion strategies or local distributors looking to partner with global brands. The specific revenue values and growth contributions for each geographic zone are detailed within the full study, enabling precise market entry planning without the guesswork.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderate level of concentration, with the top three players holding approximately 35.5 percent of the market share, while the top five control around 48.2 percent. This structure indicates a competitive environment where dominant players coexist with agile regional specialists. Understanding the strategies of these key competitors is essential for maintaining market position.
Leading global entities such as ABB, headquartered in Zurich, continue to strengthen their portfolio with specific series like MS116 and MS132, focusing on compact units that integrate protection and control. Schneider Electric, based in France, maintains a strong presence with the TeSys Deca GV2 and GV3 series, recently updating their catalog with TeSys Deca Advanced solutions in late 2025. Eaton, from Dublin, offers robust options like the PKZM and Cutler-Hammer B100 series, catering to diverse machinery control needs.
Siemens remains a key player with their 3RV2 series, serving the high-standard European and global markets. Meanwhile, specialized players are carving out niches. NOARK Electric, based in California, recently expanded their offering with the Ex9S80 Manual Motor Starter in mid-2025, emphasizing built-in fault indication. Fuji Electric in Tokyo continues to innovate with their Duo Series, while Appleton Electric, part of Emerson in Illinois, focuses on factory-sealed starters for hazardous locations. LS Electric in South Korea contributes with their Metasol MMS series, highlighting the global nature of this supply chain.
Competitive strategy in this market is not just about price. It is about compliance, reliability, and product features. Companies must navigate specifications such as short-circuit breaking capacity up to 100 kA at 400 VAC. Failure to meet these technical benchmarks can disqualify a product from key tenders. Our analysis examines the recent developments and product launches of these key companies to identify trends in innovation and market share shifts. The full report details the specific strategic moves and product portfolios that are defining the competitive edge in 2026.
Regulatory Environment and Technical Standards
Compliance is a non-negotiable aspect of the manual motor starter business. These electromechanical devices serve as the first line of defense for manual isolation, control, and overcurrent protection. They must adhere to rigorous international standards, including IEC and UL certifications. The regulatory landscape is tightening, particularly in hazardous environments.
For instance, starters designed for use in hazardous locations, such as Class I, Division 1 and 2 areas, require specific factory-sealed designs to prevent ignition sources. This creates a barrier to entry for lower-quality manufacturers and rewards established brands with proven certification histories. Furthermore, the average selling price of industrial-grade manual motor starters typically ranges from 150 to 450 USD, depending on current ratings between 10A and 100A and the complexity of protection features.
This pricing structure reflects the cost of compliance and engineering quality. Procurement teams must balance budget constraints with the inherent risks of non-compliance. Our research evaluates how regulatory changes are impacting product design and pricing strategies across the industry. We analyze the compliance requirements that are becoming key differentiators in procurement bids. Detailed regulatory impact assessments for specific regions and application types are included in the comprehensive study.
Investment and Procurement Outlook for 2026
As organizations move into the 2026 fiscal year, capital allocation decisions must be informed by data. The forecast growth to 768.22 Million USD by 2030 suggests a sustained demand environment. For procurement leaders, this means securing supply chains early to mitigate potential shortages or lead time extensions. For manufacturers, it means scaling production capabilities in line with the 4.3 percent to 4.5 percent growth corridors identified in our models.
The period from 2026 to 2032 will likely see consolidation among smaller players and increased investment in product features that enhance safety and diagnostics. Companies that adapt to these trends will capture greater market share. Those that rely on legacy designs without adapting to newer safety standards risk obsolescence.
Strategic planning also involves understanding the cyclical nature of the industries served. While manufacturing may fluctuate with economic cycles, utilities and water management often provide stable, recurring revenue. A diversified portfolio approach is recommended for market players. Our report provides the scenario planning tools necessary to model revenue under different economic conditions.
Why This Report is Essential for Decision Makers
In an era of information overload, clarity is the most valuable commodity. This report cuts through the noise to provide verified data, expert analysis, and forward-looking insights. It is not just a collection of numbers; it is a strategic framework for understanding the Manual Motor Starters Market.
By utilizing this research, your organization can:
- Benchmark your internal forecasts against independent market projections for the 2026-2032 period.
- Identify high-growth segments and regions before competitors do.
- Understand the competitive moves of key players like ABB, Schneider Electric, and Eaton to anticipate market shifts.
- Navigate regulatory complexities with confidence, ensuring product compliance and market access.
- Optimize supply chain strategies based on regional demand nuances and historical performance data from 2020 to 2025.
The market size data provided in the introduction offers a glimpse into the potential, but the actionable intelligence lies in the segmentation, competitive analysis, and regional breakdowns that are fully detailed in our complete study. The specific revenue splits by type, application, and region, along with the in-depth company profiles and recent development timelines, are critical for forming a precise strategy.
Access to the full report unlocks the detailed segmentation splits, such as the specific contributions of AC versus DC starters and the exact market valuation for industrial manufacturing versus other applications. It also provides the granular regional data necessary for local market planning. In a market projected to reach 857.0 Million USD by 2032, knowing exactly where to focus resources is the difference between average performance and market leadership.
Conclusion
The Manual Motor Starters Market offers a landscape of steady opportunity for those equipped with the right intelligence. As the industry moves past the base year of 2025 and into the forecast horizon, the convergence of regulatory pressure, technological refinement, and industrial demand will define the winners. PW Consulting's latest research provides the lens through which to view this future. We invite stakeholders to leverage this comprehensive analysis to drive informed decision-making and secure a competitive advantage in the years to come.
For those ready to transform data into strategy, the full market intelligence report is available for review. Engage with our detailed findings to align your organizational roadmap with the definitive market trajectory.
For detailed analysis of this topic, please visit the official page: Manual Motor Starters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Smart Elevators And Escalators Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
Global Smart Elevators And Escalators Market: by Type (Smart Elevators, Smart Escalators), Application (Residential, Commercial, Industrial, Institutional, Mixed-use Buildings, Others), Distribution Channels (Direct Sales, Distributors, Online, Retail, Value Added Resellers, Others), Technology (Automation, Control Systems, Security & Access Systems, Energy Efficiency Solutions, IoT Integration, Advanced Display Systems), Organization Size (Small, Medium, Large) and By Global – Historical & Forecast Period (2020-2035) Comprehensive Study 2025
Read More - https://bussinessinsights.com/research-report/global-smart-elevators-and-escalators-market
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-smart-elevators-and-escalators-market
Frequently Asked Questions
Who are the key players in Global Smart Elevators And Escalators Market industry?
The top five players in the industry are Otis Elevator Company, KONE Corporation, Schindler Group, Thyssenkrupp AG, and Mitsubishi Electric Corporation. These companies lead the market through technological innovation, extensive global presence, strategic partnerships, and a wide portfolio of smart, energy-efficient elevator and escalator solutions.
What is the Global Smart Elevators And Escalators Market growth?
The Global Smart Elevators and Escalators Market is experiencing robust growth, driven by rising urbanization and demand for energy-efficient transport in buildings. In 2023, KONE Corporation reported significant new installations supported by smart digital services, reflecting the sector’s above-average annual growth rate of over 6%.
Which segment accounted for the largest Global Smart Elevators And Escalators Market share?
The largest market share in smart elevators and escalators is held by the commercial segment. Increased deployment in office buildings, commercial complexes, and malls is driving demand, as these applications benefit from advanced access control and energy-saving technologies, optimizing traffic flow and ensuring enhanced user safety and convenience.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com